2026 Global Fixed Income Outlook
Fourth Quarter
Key Takeaways
Treasury yields have been rising in response to inflation, Federal Reserve (Fed) uncertainty and mounting federal debt.
While the market’s concerns are valid, we believe maintaining a broader perspective and focusing on active management are key to navigating the backdrop.
The synchronized rise in global yields suggests demand for a higher term premium but no explicit concern about the U.S. fiscal condition yet.
Why Are Treasury Yields Rising?
The recent surge in Treasury yields, including a nearly 20-year high for the 30-year Treasury bond, has many investors on edge. Rising yields typically signal higher borrowing costs, inflation concerns and worries about the volume of government debt.
Higher yields also drive down the prices of existing bonds, creating potential total-return challenges for some fixed-income investors.
While all these factors characterize today’s bond market, it’s important to understand why yields have been climbing. It’s also crucial to maintain historical and global perspectives.
How Does Government Debt Affect Treasury Yields?
After decades of unchecked federal spending, the U.S. now faces long-term threats to its fiscal position and its ability to repay its debt. The U.S. Treasury market is finally responding.
The U.S. national debt recently surpassed $40 trillion, exceeding the nation's gross domestic product (GDP) by nearly $8 trillion.1 This pushed the country’s debt-to-GDP ratio to nearly 126%, the third highest among the world’s major economies, according to the International Monetary Fund.
This massive, record-level debt has put pressure on Treasury yields, particularly long-maturity securities. Rising Treasury yields can ripple through financial markets, triggering higher mortgage and auto loan rates, higher corporate bond yields and higher infrastructure financing costs. Investors worry these factors could slash consumer spending, housing activity, corporate investment and economic growth.
Additionally, as Treasury securities issued several years ago (when interest rates were ultra-low) mature, the government’s interest costs are rising. That’s because refinancing existing debt — and funding new government spending — now costs more. Interest rates have risen notably since the near-0% levels of the pandemic era and the global financial crisis.
Through July 2026, the 10th month of fiscal 2026, the federal government’s cumulative interest expense totaled $931 billion.2 Interest costs now exceed U.S. defense spending and represent the third-largest government expenditure, behind only Social Security and Medicare.3
Nevertheless, today’s interest cost as a percentage of GDP (approximately 3.2%) is only slightly higher than it was in the late 1990s, as Figure 1 illustrates.
Figure 1 | Federal Interest Costs, Treasury Yields on the Rise
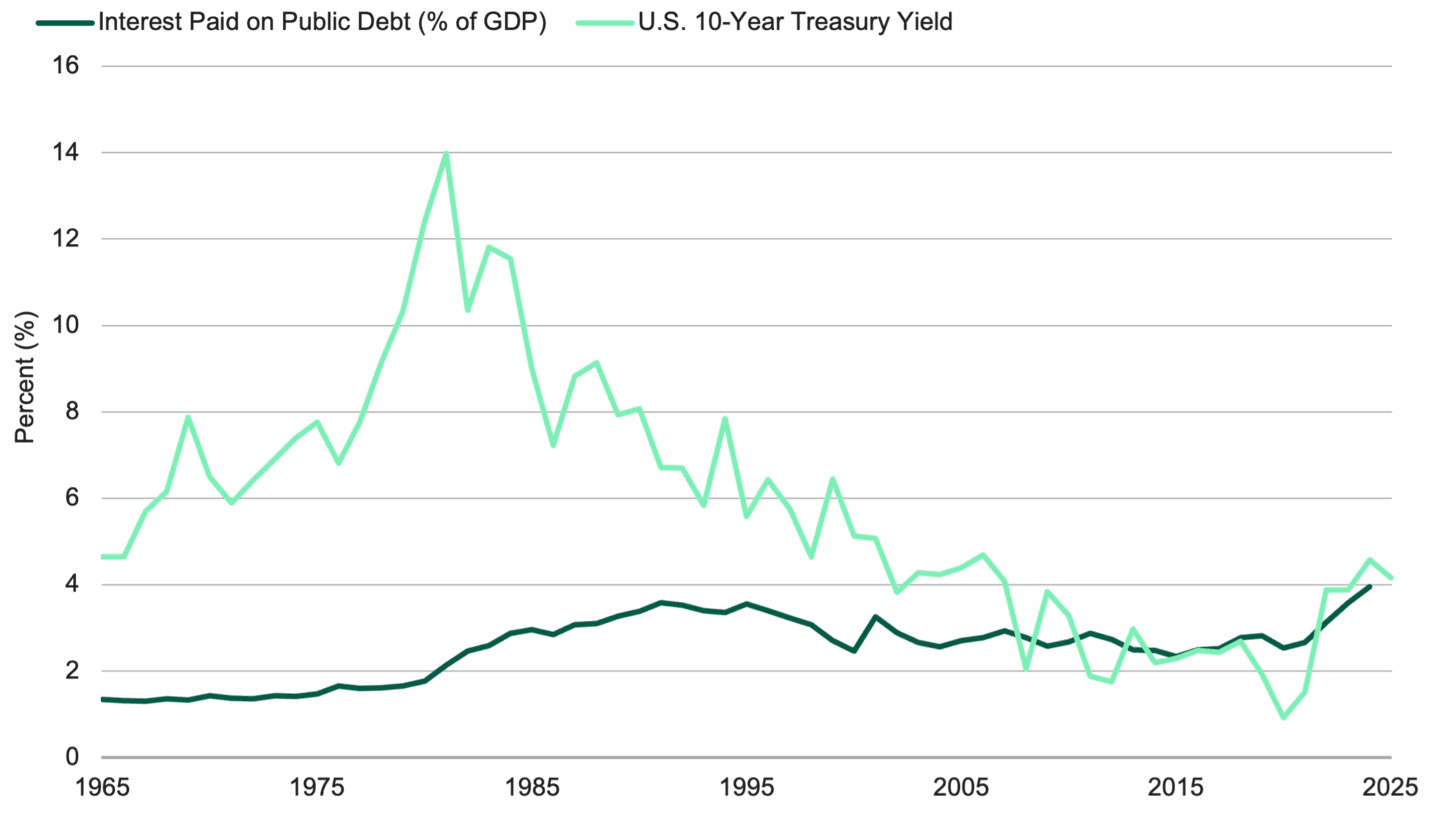
Data from 12/31/1965 – 12/31/2025. Source: FactSet.
As additional lower-cost debt matures and the government refinances that debt, federal borrowing costs are likely to continue rising. The Congressional Budget Office projects interest payments may double in 10 years, rising from $1 trillion in 2026 to $2.1 trillion in 2036.4
How Do Inflation and Government Debt Affect Global Bond Yields?
It’s important to note that the U.S. isn’t the only country facing higher yields. Across developed markets, similar factors — including elevated inflation and soaring government deficits and debt — are driving global bond yields higher. Figure 2 illustrates this trend.
Figure 2 | Yields Have Been Rising Across Developed Markets
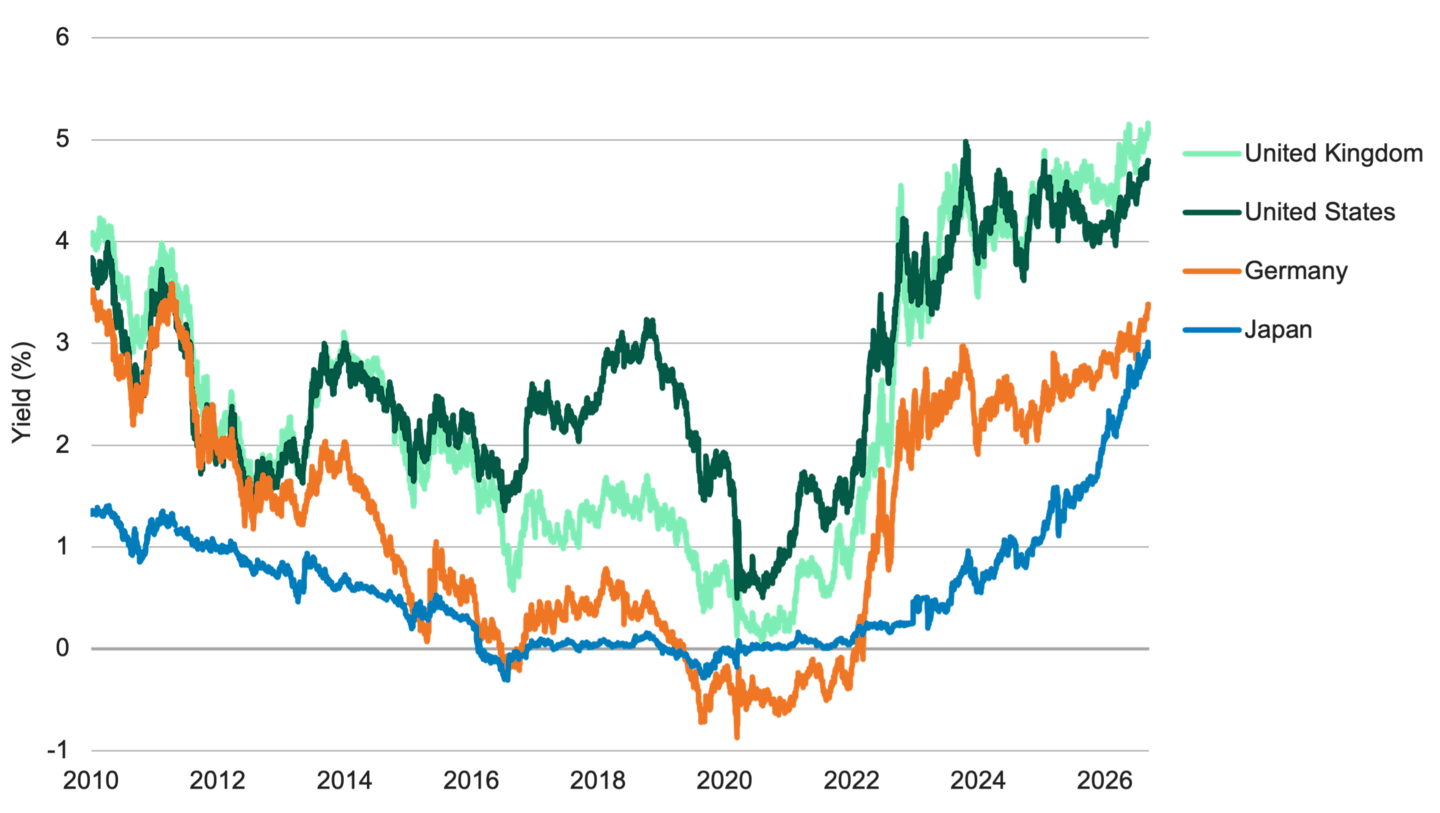
Data from 1/1/2010 – 8/31/2026. Source: FactSet.
Additionally, we believe hyperscalers (large tech companies that operate massive global networks of data centers), debt issuance and artificial intelligence (AI)-related capital spending are reshaping the global investment backdrop. Spending on data centers, power infrastructure and AI capacity is driving robust demand — and competition — for longer-duration capital. This dynamic is further pressuring the long end of the Treasury yield curve.
These factors help explain why long-maturity rates have moved more than short-maturity rates. Additionally, in recent years, the world has been undergoing a regime change, from a savings glut to a savings shortage. This transition is contributing to the global rise in rates.
Are Rising Term Premia Only a U.S. Phenomenon?
For many years, anchored inflation and central banks’ quantitative easing and predictable policy reactions largely suppressed longer-maturity yields. But market dynamics have shifted, triggering a rise in the term premium. This refers to the extra compensation investors demand for holding longer-maturity bonds rather than continually rolling over short-maturity securities.
Across developed markets, bond investors are demanding higher compensation amid inflation volatility, fiscal uncertainty and supply risk. That suggests real yields may remain higher than what investors have been accustomed to since the global financial crisis.
Although the U.S. 10-year term premium has been rising since the pandemic, it remains well within the range observed over the past three decades. To the surprise of many investors, the U.S. term premium has been lower than the term premia for government bonds in Japan, Germany, and the U.K.
In our view, this suggests that market expectations for Fed rate hikes may be the main factor driving U.S. rates higher. Additionally, global dynamics indicate that the market views the U.S. fiscal backdrop as less worrisome than the fiscal situations in other countries.
—
¹$32.5 trillion, annualized as of the second quarter of 2026
²Peter G. Peterson Foundation, “Interest Costs on the National Debt,” July 2026.
³Peter G. Peterson Foundation, “Interest Costs on the National Debt,” July 2026.
⁴Ibid.
U.S. Government Bonds
We expect the Fed to maintain a tightening bias and yields to remain elevated into year-end. High energy prices are causing persistent inflation concerns in the market, even while we expect core inflation to remain relatively stable or soften somewhat into 2027.
As such, we expect the 10-year Treasury yield to generally trade in a range of 4.5% to 5%. We also expect the yield to occasionally move above 5%, offering potential opportunities to extend portfolio duration.
U.S. Securitized Assets
Securitized markets have remained relatively insulated from market responses to mixed economic data and ongoing geopolitical uncertainty. We continue to evaluate opportunities across the sector, focusing on potentially increasing floating-rate credit exposure and reducing our agency mortgage-backed securities (MBS) allocation. If interest rates rise or volatility increases, we believe this strategy could enhance relative performance.
Among asset-backed securities (ABS), supply remains robust, particularly for data center and consumer assets. We continue to see value in select A-rated assets with attractive yields. Elsewhere, we believe commercial mortgage-backed securities (CMBS) may offer opportunities due to their historically wide spreads and solid yields.
Municipal Bonds
Municipal credit fundamentals continue to normalize following a period of exceptional strength. With revenue growth unable to keep pace with rising expenses, and federal support declining, strong financial reserves have provided a cushion. Meanwhile, fiscal pressures, changing demographics and affordability dynamics are fueling dispersion across sectors and regions, most notably among education-related sectors.
Overall, muni valuations remain tight, reinforcing the importance of stringent security selection. We favor high-quality issuers with financial flexibility, particularly in the energy prepay, multifamily housing and development district sectors.
Additionally, we’re monitoring the potential effects the November midterm elections could have on tax policies, federal funding and state and local fiscal dynamics.
U.S. and Non-U.S. Corporate Bonds
With credit spreads near historically tight levels, we believe issuer-specific developments will be the primary driver of relative performance. Accordingly, we are emphasizing securities with identifiable catalysts and attractive risk/reward profiles.
AI-related investment continues to support growth, though increased technology-sector issuance is contributing to greater index concentration and supply. Overall, we remain constructive on investment-grade credit relative to lower-quality segments.
We expect an active M&A calendar to generate attractive investment prospects. We will look for opportunities to deploy capital into transaction-related market dislocations at favorable valuations.
Money Markets
After recently reaching record-high yields, the one-year Treasury bill index is now pricing in two more Fed rate hikes in this new cycle. In unison, we are extending fixed-rate maturities in taxable money market portfolios in an attempt to capture the full yield potential of this material move. We’re extending mostly via Treasury bills and Treasury coupons. If the Fed pauses in October (or delivers just one more hike in 2026), we potentially could realize embedded capital gains on top of gross-yield (book) performance.
Outside the government sector, we plan to focus on new-issue asset-backed commercial paper (ABCP) and callable structures offering attractive spreads. ABCP has logged record issuance so far in 2026, led by a 25% jump in the third quarter. We expect to participate as needed in effort to tame reinvestment risk and enhance diversification, as we anticipate a continued net increase in inflows into money market portfolios.
Emerging Markets (EM)
We believe valuations remain stretched, particularly for U.S. dollar-denominated investment-grade bonds, where spreads have reached historically tight levels. Accordingly, we are finding more opportunities in the high-yield segment, where select issues offer value given improving credit ratings and attractive yields. Energy price volatility remains a key driver in local markets, though resilient global growth continues to provide a tailwind, particularly for EM currencies.
Regionally, we tend to favor Latin America, a commodity exporter that delivers some of the market’s highest yields. Notably, Brazil and Colombia offer high real rates while maintaining an easing cycle despite heightened geopolitical challenges. Furthermore, recent election results in Colombia suggest a turn for the better, which should help ease the country’s high term premium.
Conversely, we’re generally avoiding Asia (except Indonesia), which offers some of the lowest yields.
Senior Vice President, Chief Investment Officer, Global Fixed Income, Senior Portfolio Manager
Explore Our Global Fixed Income Capabilities
The letter ratings indicate the credit worthiness of the underlying bonds in the portfolio and generally range from AAA (highest) to D (lowest).
References to specific securities are for illustrative purposes only and are not intended as recommendations to purchase or sell securities. Opinions and estimates offered constitute our judgment and, along with other portfolio data, are subject to change without notice.
International investing involves special risks, such as political instability and currency fluctuations. Investing in emerging markets may accentuate these risks.
Investment return and principal value of security investments will fluctuate. The value at the time of redemption may be more or less than the original cost. Past performance is no guarantee of future results.
Historically, small- and/or mid-cap stocks have been more volatile than the stock of larger, more-established companies. Smaller companies may have limited resources, product lines and markets, and their securities may trade less frequently and in more limited volumes than the securities of larger companies.
Diversification does not assure a profit nor does it protect against loss of principal.
Generally, as interest rates rise, bond prices fall. The opposite is true when interest rates decline.
Past performance is no guarantee of future results. Investment returns will fluctuate and it is possible to lose money.
The opinions expressed are those of American Century Investments (or the portfolio manager) and are no guarantee of the future performance of any American Century Investments portfolio. This material has been prepared for educational purposes only. It is not intended to provide, and should not be relied upon for, investment, accounting, legal or tax advice.
©2026 Morningstar, Inc. All Rights Reserved. Certain information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information.