Inside Washington With Jeff Bush
Decisions in the nation's capital can move markets. Get nonpartisan analysis on what’s happening in DC through the lens of a 30+ year veteran of the financial services industry.
Washington at 250 Miles Per Hour: What Matters for Investors
Washington is moving at a fitting pace as the U.S. marks its 250th year: 250 miles per hour. With policy, politics and markets colliding on multiple fronts, knowing which developments could have lasting impact isn’t easy.
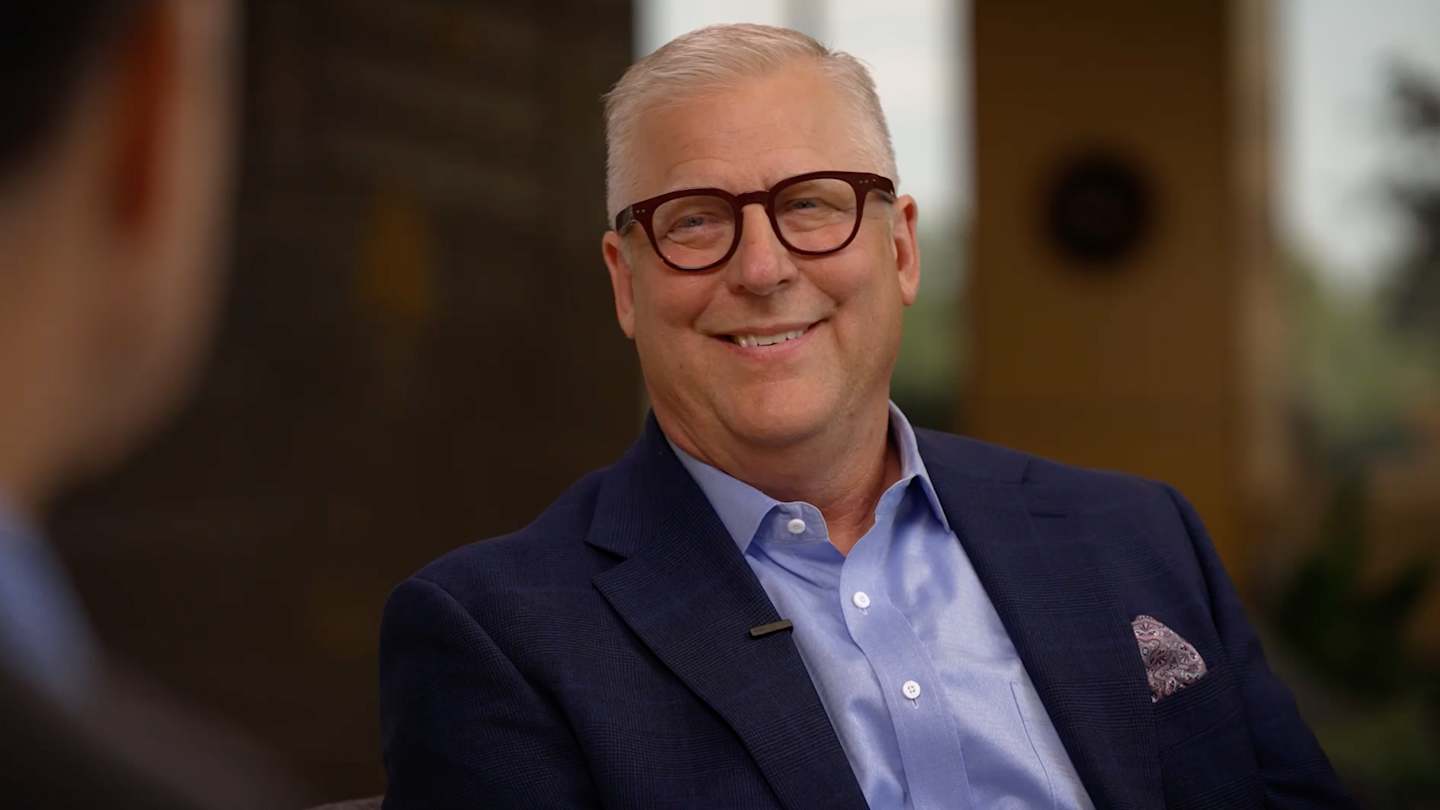
Jeff Bush, principal of The Washington Update, helps sort it out. Tune into our interview to hear his perspective on what deserves investors’ attention, what may be getting too much of it and what could be flying under the radar.
Watch now.
Recorded on August 28, 2026
Key Takeaways
Edited excerpts from our conversation with Jeff Bush.

How could the midterms play out, and how might markets respond?
I believe the Democrats will take control of the House of Representatives. I think they’ll have a good night, but because of redistricting and other things, there just aren’t that many competitive House districts. So if Democrats end up with a 10- to 12-seat majority, that’s a big win. I don’t expect a landslide because there aren't that many competitive House districts.
Where I have changed my opinion a bit is the Senate elections. I’ve said all year long that Republicans will keep the majority, and I still think that’s the base case, but now I can honestly see viable paths for the Democrats to take control of the Senate as well.
What might the election outcome mean for markets?
Markets like certainty. They like predictability. They can build plans around that. To the extent that this election goes as we anticipate and there are no big surprises one way or the other, I think the markets will be just fine with it.
Generally speaking, markets do well in a split congressional environment because it produces a period of gridlock. In gridlock, you’re not going to get big, wholesale policy changes done during that two-year period. That gives the markets time to sit, and corporations can build business plans, and you and I can build financial plans.
How worried should investors be about Social Security?
This is a very qualified answer. I think your level of concern is directly proportional to your age. The younger you are, the more concerned you should be. … Right now, the projected reduction in benefits is expected to occur around 2032. I do think that timeline could move up if we see inflation or other factors accelerate the program's funding challenges. That’s why I’m telling people 2031. And that timeframe is relevant. It’s very important because the elected officials overseeing Social Security reform will include those we elect in 2026, 2028 and 2030.
I want to be very clear. If you’re 60-plus, I really don’t think you have to worry about your Social Security benefit. One of the biggest concerns I hear as I travel around the country is people saying, ‘Well, I hear it’s going away. Should I go ahead and claim it early?’ That is not a good strategy. You really have to look at your unique situation with your financial advisor and figure out the appropriate time to take that Social Security benefit.
AI data centers have become a major concern in the midterms. Is the criticism warranted?
A lot of this negative rhetoric toward data centers, I’m just being fully transparent, is coming from China and Russia. They, specifically China, are definitely on a campaign to generate anti-AI sentiment in the United States because it benefits them in the head-to-head competition we’re in for AI. I’m a little concerned about that.
All the concerns you hear about data centers, about the water wastage, about the noise, about all those different issues, the energy usage ... a lot of that’s already been engineered out with a recirculating cooling system. It’s one load of water, and it just recycles it, kind of like the radiator in your car.
And regarding the energy use, most states now have said, ‘That’s great. We want your data center, but you’re going to bring your own energy.” It actually puts unused potential back into the grid. So theoretically, it could stabilize prices in a local community … I blame the tech industry for being horribly behind in their messaging around data centers.
Are private investments coming to 401(k)s?
I’m glad that’s kind of been a slow walk in that direction. I am a little concerned about private markets because of their opaqueness and lack of transparency. I’m not a big fan of that for the average, typical investor. They may not fully understand what’s happening there.
I do think it’s inevitable that we’re moving in that direction only because companies are staying private much longer, and that’s where we’re seeing that exponential part of their growth history taking place.
There should be some access to [private markets] inside retirement plans, like there are in brokerage accounts. But I think there are some regulatory hurdles before it can be fully and broadly implemented.
Could some taxpayers pay more under the current tax law?
There are a couple of themes I think people are really missing in the new tax law. … First of all, there is a subset of U.S. tax filers who will actually see their effective tax rate go up under this new tax code, which is a little odd considering it is a broad-based tax-reduction law.
From a political standpoint, I think the Republicans have somewhat oversold the new tax law, and I think that could be hurting them because it sounds a little tone-deaf to the way people feel in the economy today.
There’s now a 100% haircut to deductions for the Pease limitations,* for example. More Americans will be subject to the alternative minimum tax under the new tax code. Charitable giving has a little bit of a caveat. If you’re an itemizer, you get to deduct only the amount of contribution above 0.5% of your adjusted gross income.
With all these little things inside the new tax law, a unique subset of tax filers will actually see their effective tax rate go up. They generally tend to be very high-income W-2 families.
What tax-planning moves should investors consider due to changes in the tax code?
If you are an itemizing client, you need to talk to your financial advisor about the combination of donation bundling along with donor-advised funds. The combination of those two things makes charitable giving a little more powerful for that individual filer. And advisors are well-versed in the concepts of donation bundling and donor-advised funds.
Step two is to make sure you have your withholdings properly scheduled because of the changes in the tax code. We have a full year of implementation now, with a lot of things coming into place; you need to make sure you’re withholding properly. You don’t want a big tax bill in April, and you also don’t want a big tax refund. You want to get to pretty much a net-zero relationship with the federal government.
Could Trump Accounts influence how some donors think about charitable giving?
What I think is really fascinating about the Trump accounts is what’s happening with Michael and Susan Dell, for example. They caught on to this Trump account concept of direct giving to an individual in our country. So they’ve layered on top of those personal contributions to those recipients of Trump accounts. And I think that’s a really interesting philosophy of giving from the uber wealthy in a direct manner to the recipient. I think that could be a real trend that we see moving forward in our country.
Explore More Insights on Policy and the Markets
Stay informed on how government policies are shaping the economy and investment opportunities.
Named after former U.S. Representative Donald Pease, the Pease limitation was a federal tax rule that reduced total itemized deductions by 3% for every dollar a high-income earner's adjusted gross income (AGI) exceeded specific thresholds, up to a maximum reduction of 80%.
The views expressed in this presentation are the speaker’s own and not necessarily those of American Century Investments. This presentation is for general information only and is not intended to provide investment, tax or legal advice or recommendations for any particular situation or type of retirement plan. Please consult with a financial, tax or legal advisor on your own particular circumstances.
Jeff Bush and The Washington Update are not affiliated with American Century Investments.
IRS Circular 230 Disclosure: American Century Companies, Inc. and its affiliates do not provide tax advice. Accordingly, any discussion of U.S. tax matters contained herein (including any attachments) is not intended or written to be used, and cannot be used, in connection with the promotion, marketing or recommendation by anyone unaffiliated with American Century Companies, Inc. of any of the matters addressed herein or for the purpose of avoiding U.S. tax-related penalties.
This information is for educational purposes only and is not intended as tax advice. Please consult your tax advisor for more detailed information or for advice regarding your individual situation.
Investment return and principal value of security investments will fluctuate. The value at the time of redemption may be more or less than the original cost. Past performance is no guarantee of future results.