Why Active Bond ETFs May Make Sense Now
Active bond exchange-traded funds (ETFs) give investors access to fixed-income managers with the flexibility to respond to changing markets and pursue opportunities beyond an index—along with ETFs’ potential cost and tax efficiencies.
Key Takeaways
Active bond managers have the flexibility to respond to changing rate environments and pursue opportunities beyond an index.
Active strategies have more opportunities to seek diversified sources of income and return potential across bond markets and manage diverse risks.
ETFs can offer a low-cost, tax-efficient and liquid way for investors to pursue income, total return and diversification goals.
Active bond ETFs may make sense in today’s dynamic bond market because fixed-income managers can respond to market dislocations and evolving risks in real time.
As interest rates, inflation and economic conditions change, active managers can adjust duration, credit exposure and sector allocations to seek attractive income and total return potential. And the ETF structure offers an appealing way to access active management with potential cost and tax efficiencies compared with other investment vehicles.
What Are the Benefits of Active Bond ETFs?
Active fixed-income strategies generally seek to outperform a specific market index via the investment team’s market, research and security selection insights. And active fixed-income ETF managers have many tools in their arsenal to potentially add value versus passive indices.
How Can Active Bond ETFs Find More Opportunities?
Securities in broad benchmark indices may not represent the best values in the market. Finding value requires a deeper dive.
Active managers seek to uncover value across the fixed-income spectrum, including the new-issues market. They can invest in places that popular market indices often ignore, such as smaller and underfollowed sectors, securities, issuers and countries. Additionally, active managers are free to exit securities they believe have reached their valuation potential, while passive indices must continue holding them if they’re a benchmark component.
How Can Active Bond ETFs Respond to Credit Changes?
Active managers can monitor and respond to credit market trends—another potential key advantage over passive portfolios. Active managers typically rely on proprietary research and analysis. They can proactively sell securities with weakening credit quality or buy securities as credit quality improves.
Unlike their passive counterparts, they can potentially get ahead of potential credit rating changes. In addition to possibly avoiding these “fallen angels,” active managers have the flexibility to purchase “rising stars.” These are bonds poised for a credit rating upgrade from the high-yield universe to the investment-grade universe.
Active research may also help managers exploit market inefficiencies and anomalies. This feature could lead to performance advantages versus market benchmarks.
How Can Active Bond ETFs Expand Income and Return Opportunities?
Many investors seek to balance interest rate and credit risk in pursuit of attractive income and total return. Active fixed-income managers can help by evaluating and securing diversified sources of income in all interest rate environments. They have the flexibility to actively adjust sector exposures and credit quality to help enhance yield and return potential and actively manage risk.
How Can Active Bond ETFs Respond to Changing Interest Rates?
Unlike passive strategies, active managers can adjust their exposure to interest rate risk (duration) as market conditions and their outlooks change. (Shorter-duration bonds may help reduce sensitivity to rate changes while still offering attractive income potential.)
The ability to adjust duration gives active managers greater flexibility to navigate changing rate environments and may contribute to performance relative to the benchmark.
What Are the Limitations of Bond Index Funds?
Passively managed bond index funds seek to mimic the makeup and performance of a stated market index, which generally reduces fund costs versus actively managed funds. However, these strategies can expose investors to risks such as:
Overweights to big debt issuers. Within popular bond indices, issuers with the most debt usually have the largest index weightings. This means passive portfolios may be overexposed to issuers with heavy debt burdens, potential credit weakness and concentration risk.
Credit concerns. Unlike active portfolios, market indices don’t consider an issuer’s default risk or declining credit rating. This risk tends to be more prevalent in slowing economies, when credit risk typically rises. Passive strategies with investment-grade mandates may have to sell securities with declining credit ratings as their prices are falling.
Index replication constraints. Investors cannot invest directly in a market index, so fund managers must do their best to replicate the index’s composition. However, it’s unlikely that all the bonds represented in a broad market index will be available for purchase. So, index managers typically engage in sampling or optimizing in their attempts to mimic a broad fixed-income index.
Limited investment universe. Broad bond indices—and the portfolios that track them—provide exposure to longer-maturity, high-quality government, government-related and corporate bonds, as Figure 1 illustrates. Conversely, investors in actively managed portfolios may pursue more opportunities from the other sectors in the index as well as from non-index sectors, such as asset-backed, securitized, non-U.S. and high-yield securities.
Figure 1 | Government Securities Dominate Core Bond Benchmarks
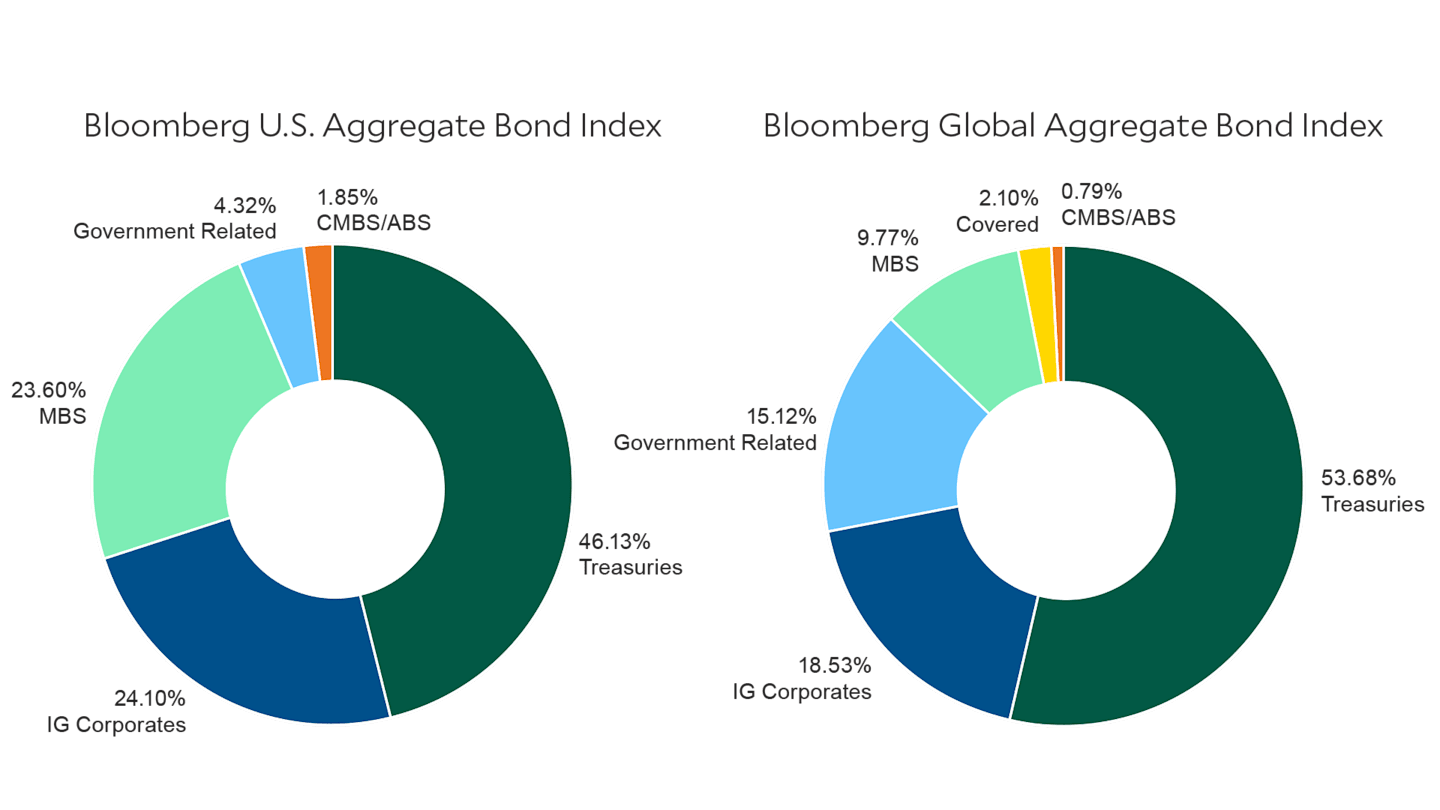
Data as of 06/30/26. Source: Bloomberg.
MBS = Mortgaged-backed securities, CMBS = Commercial mortgaged-backed securities, ABS = Asset-backed securities, IG = Investment grade
Bloomberg U.S. Aggregate Bond Index. The component of the U.S. Aggregate Bond Index that includes U.S. government-sponsored agency securities with a remaining maturity of at least one year.
Bloomberg Global Aggregate Bond Index. A broad-based measure of the global investment-grade fixed-income markets. The three major components of this index are the U.S. Aggregate, the Pan-European Aggregate, and the Asian-Pacific Aggregate Indices. The index also includes Eurodollar and Euro-Yen corporate bonds, Canadian government, agency and corporate securities, and USD investment grade 144A securities.
Covered bonds. Debt securities backed by cash flows from pools of mortgages or public sector loans. The asset pools help secure or “cover” these bonds if the originating financial institution becomes insolvent.
U.S. Treasury securities (Treasuries). Debt securities issued by the U.S. Treasury and backed by the direct “full faith and credit” pledge of the U.S. government. Treasury securities include bills (maturing in one year or less), notes (maturing in two to 10 years) and bonds (maturing in more than 10 years). They are generally considered among the highest quality and most liquid securities in the world.
Government Related securities. Includes government agency, local authority, sovereigns and supranational debt securities.
What Are the Risks of Active Bond ETFs?
All investments, including active bond ETFs, involve risks. Managing transaction costs, mitigating high-risk exposures, maintaining portfolio liquidity and staying informed on market volatility are among the important considerations for active investors.
The fees associated with actively managed ETFs are typically higher than the fees on passively managed portfolios. That’s because active funds call on professional investors to research markets, select securities and manage portfolio exposures and risks to pursue outperformance potential.
Conversely, passive funds pursue a less costly strategy of replicating an index with the goal of matching the benchmark’s results.Active strategy performance relies on managers' skills, experience and security selection abilities, and there is a risk that they may not achieve the desired outcomes.
Overall, active managers have had varying degrees of historical success. Outperforming a benchmark can be challenging, particularly within certain asset classes and market segments. That said, investors often turn to actively managed funds when volatility escalates or the economy falters, as managers can employ strategies that may help counter market uncertainty.
No investment strategy can ensure a profit or eliminate the risk of loss. When market and economic conditions change, it’s possible for actively and passively managed ETFs to lose value.
Our Bond ETFs Are Deeply Rooted in Active Management
American Century Investments has been managing active fixed-income portfolios for more than 50 years. We have continually expanded our investment capabilities across taxable and tax-exempt fixed-income solutions.
Our strategies are deeply rooted in active management, relying on experienced analysts and portfolio managers. Our teams build portfolios bond by bond, using in-depth proprietary research and seeking to minimize risks inherent in indexed strategies.
American Century Investments Active Bond ETFs
Our active bond ETFs feature investment teams that apply fundamental, bottom-up analyses to assess creditworthiness and relative value to dynamically adjust as opportunities emerge.
A subset of our extensive fixed-income platform includes ETFs targeting different duration ranges:
Ultrashort Income ETF (FUSI) invests primarily in investment-grade floating-rate instruments and offers an ultrashort duration (less than one year).
Short Duration Strategic Income ETF (SDSI) invests in a diverse portfolio of investment-grade, high-yield, securitized and emerging markets debt securities. The fund seeks high levels of current income and attractive risk-adjusted returns while maintaining a short duration (three years or shorter).
Core Plus Income ETF (ABND) seeks to provide income and total return in an intermediate duration strategy, and acts as a core fixed-income foundational solution that targets attractive yield throughout the market cycle. With an investment grade focus ABND has the flexibility to pursue incremental income and total-return opportunities across sectors.
Each fund shares a philosophy and investment approach. The funds seek to increase income across multiple sectors while moderating interest rate and credit risks, consistent with each fund’s individual objective.
As a diversifier for core bond portfolios, we offer Diversified Corporate Bond ETF (KORP). This portfolio emphasizes intermediate-maturity, investment-grade corporates while dynamically allocating up to 35% of its assets to high-yield corporates. Top-down analysis determines KORP’s allocation to high yield, while bottom-up research drives security selection and sector, industry and duration exposures.
Why Active Bond ETFs May Matter Now
We believe today’s bond market rewards flexibility. Unlike passive strategies tied to an index, active bond ETFs give managers the ability to respond as interest rates, credit conditions and market opportunities change. Combined with the potential cost and tax efficiencies of ETFs, that flexibility may help investors pursue income, total return potential and diversification across changing market environments.
American Century Investments brings decades of active fixed-income experience to a range of bond ETFs designed for different investor needs.
Authors
Senior Director, Product Management
Explore More Insights
FUSI, ABND, SDSI and KORP:
These funds are actively managed ETFs that do not seek to replicate the performance of a specified index. To determine whether to buy or sell a security, the portfolio managers consider, among other things, various fund requirements and standards, along with economic conditions, alternative investments, interest rates and various credit metrics. If the portfolio manager considerations are inaccurate or misapplied, the fund's performance may suffer.
Generally, as interest rates rise, the value of the bonds held in the fund will decline. The opposite is true when interest rates decline.
FUSI:
The interest rate and corresponding payment that floating rate securities are expected to pay adjust at predetermined dates on a periodic basis. Securities with floating interest rates are generally less sensitive to interest rate changes than securities with fixed interest rates, but they may decline in value if their interest rates do not rise as much, or as quickly, as comparable market interest rates. In addition, floating rate securities held by the fund may be less liquid or more difficult to sell than other securities. If it becomes necessary for the fund to sell less liquid securities, it could have an adverse effect on the fund, especially during periods of market turbulence or unusually low trading activity.
The value of the securities that the fund principally invests in may be secured or backed by other underlying assets or obligations. As such, the value of these securities may affected by the market value of the underlying assets, changes in the distributions on the underlying assets, defaults and recoveries on the underlying assets, capital gains and losses on the underlying assets, prepayments on underlying assets and the availability, prices and interest rate of underlying assets. In addition, these securities may be subject to number of additional risks, including interest rate, market, credit and correlation risk. Use of certain types of these securities can create economic leverage in the fund's portfolio, which may result in significant volatility and cause the fund to participate in losses in an amount that exceeds the fund's initial investment. Also, the value of these securities may decrease based on the inability or perceived inability of a security's issuer or obligated party to make interest and principal payments.
ABND:
International investing involves special risks, such as political instability and currency fluctuations. Investing in emerging markets may accentuate these risks.
FUSI, ABND and SDSI:
The lower rated securities in which the fund invests are subject to greater credit risk, default risk and liquidity risk.
ADND and SDSI:
Derivatives may be more sensitive to changes in market conditions and may amplify risks.
SDSI:
Duration, which is an indication of the relative sensitivity of a security's market value to changes in interest rates, is based upon the aggregate of the present value of all principal and interest payments to be received, discounted at the current market rate of interest and expressed in years. The longer the weighted average duration of the fund's portfolio, the more sensitive its market value is to interest rate fluctuations. Duration is different from maturity in that it attempts to measure the interest rate sensitivity of a security, as opposed to its expected final maturity.
Investment return and principal value of security investments will fluctuate. The value at the time of redemption may be more or less than the original cost. Past performance is no guarantee of future results.
Generally, as interest rates rise, the value of the bonds held in the fund will decline. The opposite is true when interest rates decline.
Diversification does not assure a profit nor does it protect against loss of principal.
IRS Circular 230 Disclosure: American Century Companies, Inc. and its affiliates do not provide tax advice. Accordingly, any discussion of U.S. tax matters contained herein (including any attachments) is not intended or written to be used, and cannot be used, in connection with the promotion, marketing or recommendation by anyone unaffiliated with American Century Companies, Inc. of any of the matters addressed herein or for the purpose of avoiding U.S. tax-related penalties.
This information is for educational purposes only and is not intended as tax advice. Please consult your tax advisor for more detailed information or for advice regarding your individual situation.
Exchange Traded Funds (ETFs): Foreside Fund Services, LLC - Distributor, not affiliated with American Century Investment Services, Inc.
Exchange Traded Funds (ETFs) are bought and sold through exchange trading at market price (not NAV), and are not individually redeemed from the fund. Shares may trade at a premium or discount to their NAV in the secondary market. Brokerage commissions will reduce returns.
This material has been prepared for educational purposes only. It is not intended to provide, and should not be relied upon for, investment, accounting, legal or tax advice.
You should consider the fund's investment objectives, risks, charges and expenses carefully before you invest. The fund's prospectus or summary prospectus, which can be obtained by visiting americancentury.